Chapter 5 - THE MEN WHO LAUGHEDI remembered every man who laughed when Conrad kicked me.
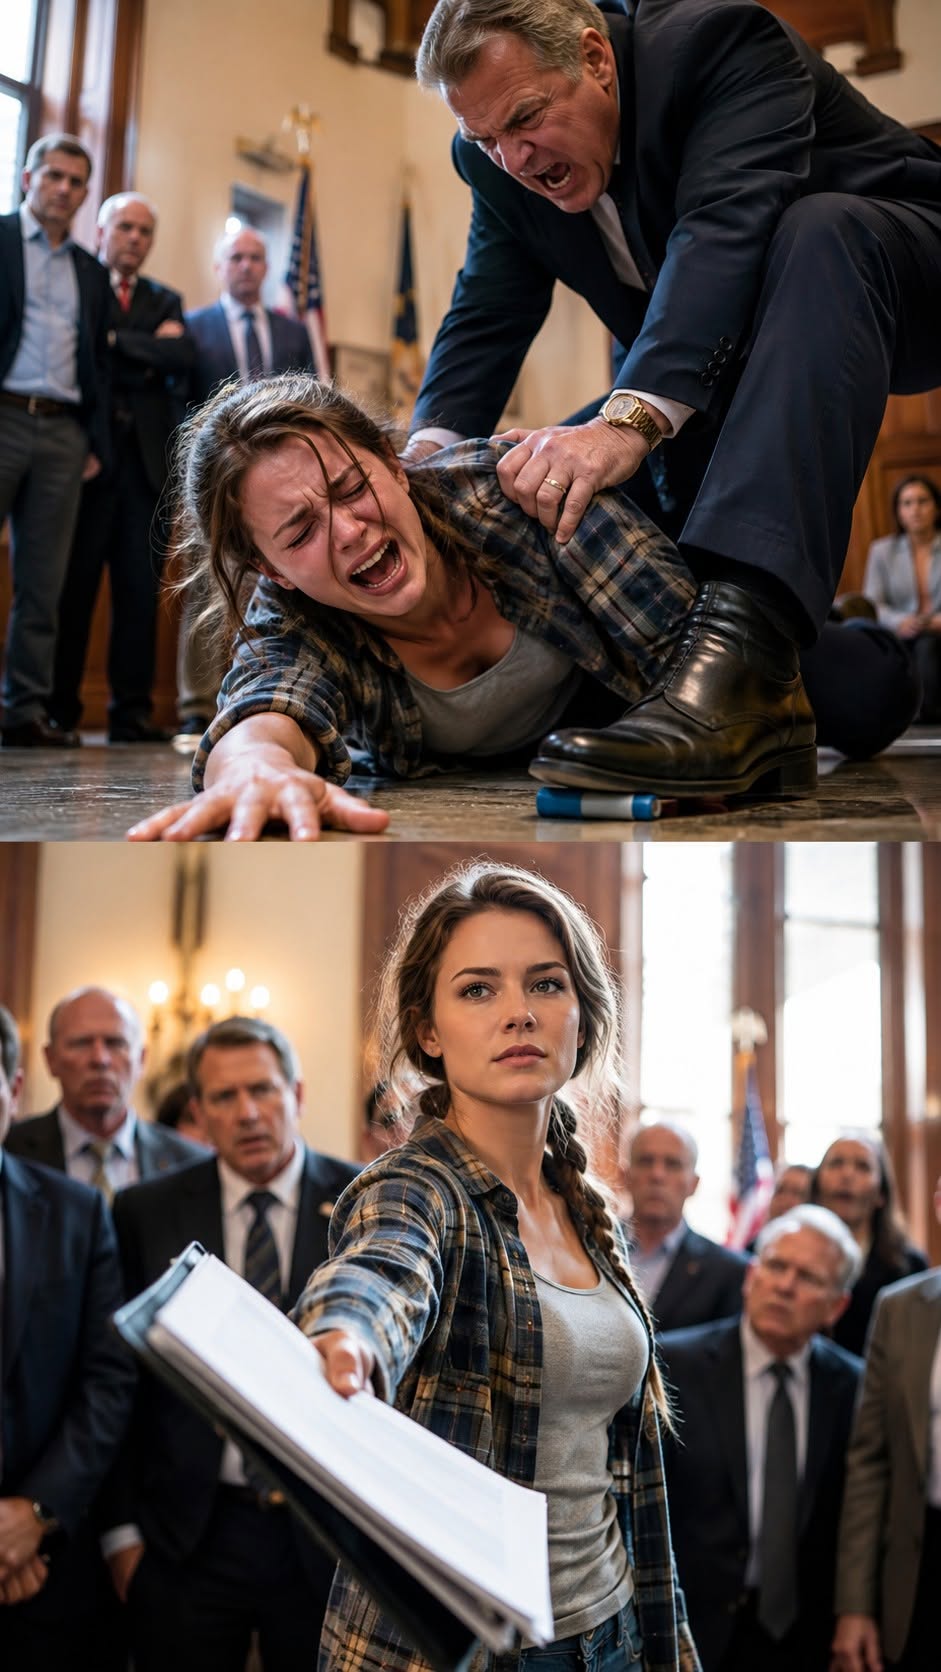
That was not useful.
I still remembered.
Councilman Peter Hale came to the farm two days after the hearing.
I met him on the porch.
No invitation inside.
He removed his hat.
“I owe you an apology.”
“Yes.”
He flinched.
Probably expected me to make it easier.
“You laughed.”
“I was shocked.”
“You laughed.”
“Yes.”
He looked toward the yard.
“I shouldn’t have.”
“No.”
“I also didn’t realize he’d stepped on your inhaler.”
“You watched him.”
“Yes.”
Silence.
Then:
“I need to tell you something about the demolition vote.”
That earned him another minute.
Hale explained that Conrad held private meetings with four councilmen before the hearing.
He told them Stonegate would walk unless demolition passed.
If Stonegate walked, Fairwick would face:
A two-million-dollar contractual claim.
Immediate refinancing trouble.
Possible layoffs.
Property-tax increases.
Conrad framed the choice:
One farm or the town’s solvency.
“Did he tell you he’d already spent redevelopment money preparing my property?”
“No.”
“Did he tell you the engineering report didn’t condemn the house?”
“No.”
“Did you read it?”
Hale looked ashamed.
“Not fully.”
I almost laughed.
Then didn’t.
Not reading had consequences.
“Why are you telling me now?”
“Town Attorney Stern called an executive session. The debt documents matter.”
“What about them?”
“I don’t understand.”
At least honest.
“He said if you control enough of the notes, the authority may need noteholder approval before taking on replacement financing.”
Still not the full secret.
Enough.
“What is Conrad planning?”
“Emergency loan.”
“How much?”
“Three and a half million.”
My stomach tightened.
“To pay Stonegate?”
“Partly. Debt service too.”
New debt on top of old debt.
Classic.
“Who’s the lender?”
Hale shook his head.
“I don’t know.”
He left.
I did not forgive him.
He had done one useful thing.
Different.
That afternoon, Naomi obtained the emergency-loan term sheet.
Lender:
Midland Commercial Bank.
Borrower:
Fairwick Redevelopment Authority.
Guarantee support:
Town of Fairwick, subject to council approval.
Collateral:
Available redevelopment revenues and proceeds from Stonegate disposition.
Meaning the loan assumed my land would eventually be sold to Stonegate.
Again.
My property appeared inside someone else’s financing model before they owned it.
Then came the covenant.
No additional senior indebtedness without consent of holders representing a majority in principal amount of outstanding 2019 redevelopment notes.
Naomi looked at me.
“There.”
I knew.
Still, we verified.
“How much principal is outstanding now?”
“Trustee calculation is pending redemptions.”
“How close am I?”
She smiled slightly.
“Very.”
Not good enough.
Exact numbers matter.
Then my broker called.
“One final block just came available.”
“How much?”
“Six hundred thousand face.”
“Seller?”
“First County.”
At forty-one cents.
I did the math.
Buying it would consume almost every liquid reserve Whitfield Farm had outside operating cash.
Harvest was two months away.
Fuel bills coming.
Fertilizer.
Payroll.
Insurance.
I stared at the numbers.
If I bought the block, I might gain a majority.
If I bought it and prices fell further, I could lose hundreds of thousands.
If I did not, Midland might refinance Conrad around me.
My father’s voice returned:
Never fall in love with a position because you want to be right.
I called the broker.
“Give me an hour.”
Then the weather alert arrived.
Severe storms.
Hail risk.
May you like



Exactly what a cash-strapped farm needed.
For the first time since buying Fairwick’s debt, I wondered whether I had risked the farm trying to save the farmhouse.
Related Stories







