Chapter 10 - WHAT MY HOUSE WAS SUPPOSED TO FIX
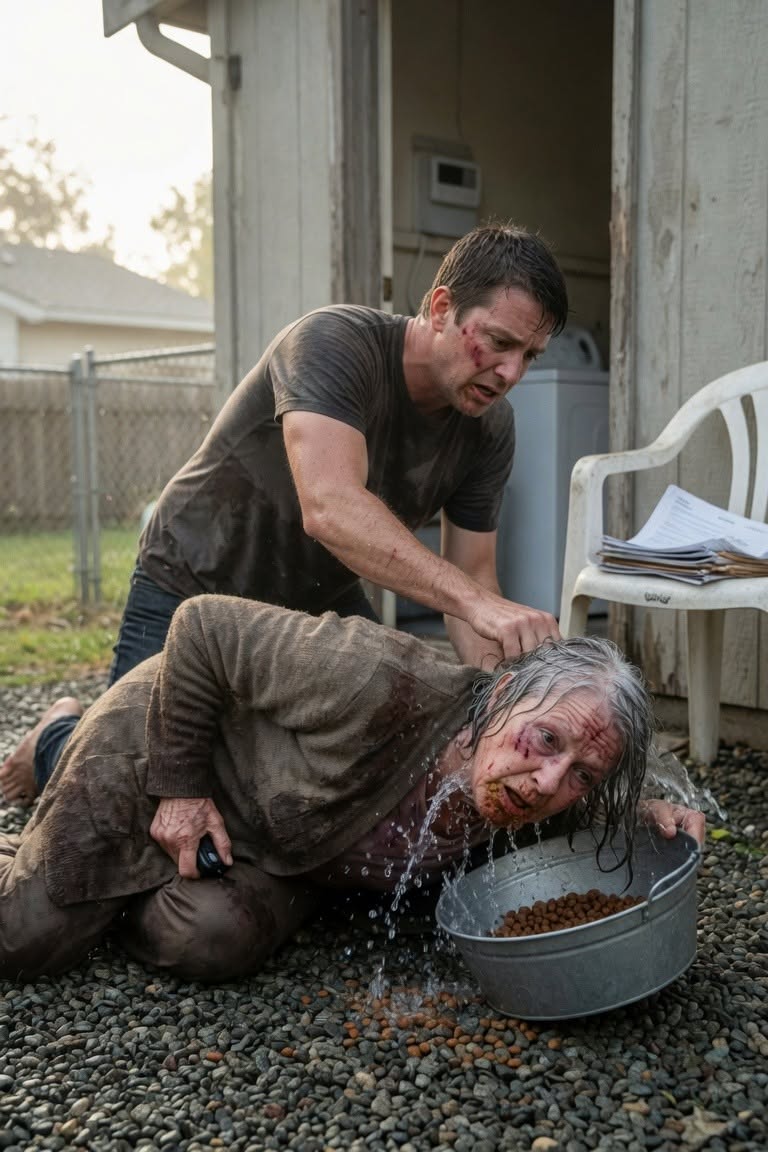
By the time the forensic reconstruction was complete, there was no mystery left about the core plan.
Only consequences.
Evan’s business had begun slipping eighteen months earlier.
One delayed project consumed another project’s deposit.
A lawsuit froze expected payment.
Payroll came due.
He moved money.
Then moved more money to replace the first transfer.
Not all of it was necessarily criminal at the beginning.
Eventually the bookkeeping crossed lines he knew existed.
Client deposits covered unrelated work.
My “temporary” money plugged refunds.
Claire’s loan covered payroll.
Tax payments were postponed.
Evan kept believing one profitable closing would reset everything.
Then North Ridge offered a bridge loan.
$225,000 immediately against business assets and Evan’s personal guarantee.
Up to another $185,000 if he supplied additional real-estate collateral.
He chose my house.
Not because I had offered it.
Because it was paid off.
Worth enough.
Close enough.
Family.
Mercer Property Holdings LLC was created to receive title from me.
The LLC would then pledge the property to North Ridge.
The second loan tranche would cover most of the remaining project shortfall before Monday’s state audit.
My bank-access authorization would let Evan establish required property reserves and move funds for taxes, insurance, and closing costs.
The durable power of attorney would make future transactions easier if questions arose.
The beneficiary form would redirect one investment account to the LLC’s debt plan if I died during the loan term.
Not murder.
Not a death plot.
Paperwork designed to make his emergency survive me.
The copied signature on the preliminary deed made North Ridge believe closing was nearly complete.
His message to Claire made sure she stayed away.
The online notary defect prevented early recording.
Then I refused.
Evan had hours.
Not weeks.
That morning his regulator emailed:
Failure to provide cure documentation by Monday may result in immediate suspension proceedings.
North Ridge emailed:
Collateral originals required today to maintain secondary funding commitment.
His bookkeeper emailed:
We cannot cover Friday payroll.
Three deadlines.
One house.
One mother saying no.
He drove to me carrying papers.
He had already told everyone I signed.
When I refused, he took my phone.
When I tried to go inside, he blocked me.
When I shouted, he pushed me toward the backyard.
Then came the basin.
Dog food.
Gravel.
“Sign the papers.”
The plan was not brilliant.
That was what frightened me.
It was desperate.
Built from years of people accepting Evan’s next promise.
Including me.
Naomi placed the final timeline on the table.
Claire sat beside me.
“What happens now?”
“Criminal prosecutors decide assault and financial charges. The contractor regulator decides license issues. North Ridge enforces its legitimate loan against Evan’s business collateral. Bankruptcy may follow. Marian pursues the unauthorized transfers and title protections.”
“And the house?”
“Marian owns it.”
I closed my eyes.
Mine.
Still mine.
Then Naomi slid one last document toward me.
“What is that?”
“A draft assisted-living application found on Evan’s laptop.”
I opened it.
My name.
My date of birth.
My insurance information.
Proposed move-in date:
Six weeks after the planned house transfer.
I looked at Claire.
May you like



For ten chapters, I had believed Evan wanted my house because his business was dying.
Now I saw what he planned to do with me after he got it.







