Chapter 4 - Paper billionaires
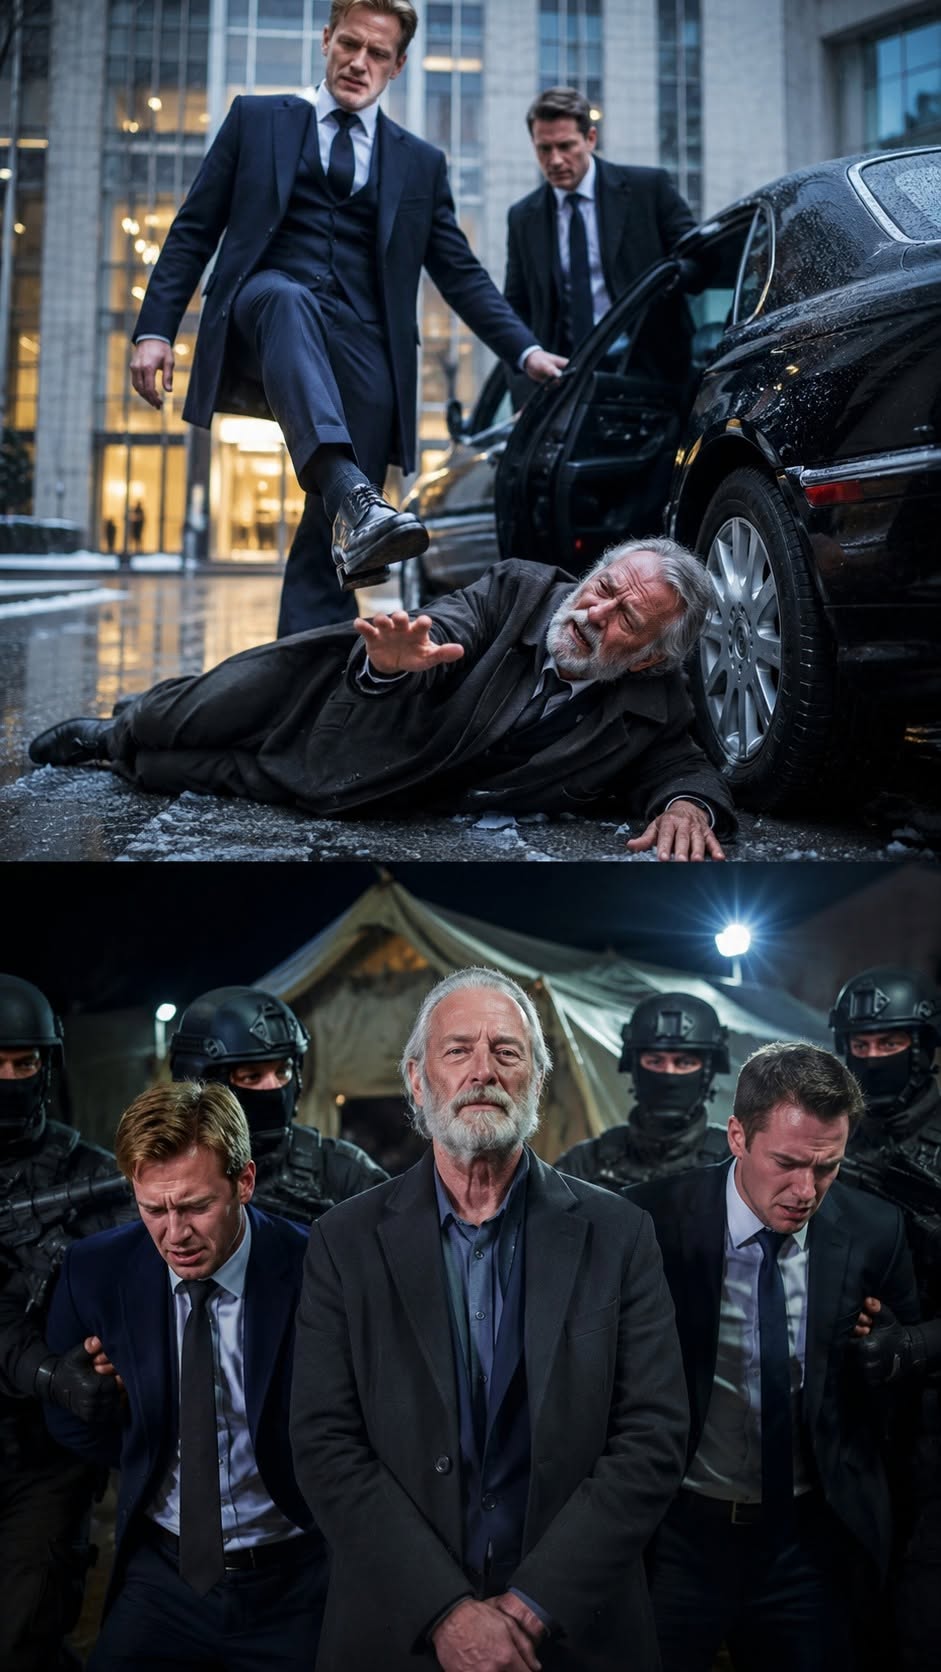
Daniel and Marcus were wealthy.
Actually wealthy.
I refuse the comforting lie that spoiled sons never built anything.
Daniel did.
Marcus did.
I gave them ladders.
They climbed.
Daniel transformed Whitmore Meridian from a slow industrial conglomerate into a technology-and-logistics platform.
Some acquisitions were brilliant.
Some overpaid.
Overall, the company’s valuation rose.
Marcus built the private-investment arm from $600 million under management to more than $4 billion.
He could read a balance sheet faster than most people read menus.
Business publications estimated Daniel’s holdings at $1.4 billion.
Marcus’s around $1.1 billion.
Those estimates assumed private-company valuations.
Their liquid wealth was far smaller.
Still enough that no one would call them ordinary rich.
So why did they care about my remaining fortune?
Control.
Humans rarely stop wanting more simply because needs disappear.
My residual estate included:
High-vote Whitmore shares.
A diversified investment portfolio.
Real estate.
Private funds.
Cash.
A family ranch I disliked.
Total value depended on company stock.
Roughly $620 million in the year before my heart attack.
My sons knew there was substantial wealth.
They did not know exactly how my updated estate plan handled it.
Before the sidewalk, the broad structure was:
Thirty percent of my remaining estate to Daniel’s continuing trust.
Thirty percent to Marcus’s.
Twenty percent to grandchildren in independent trusts.
Twenty percent to the Whitmore Foundation.
The most important asset was not the money.
Voting shares.
Under my plan, Daniel and Marcus were eventually supposed to share family voting influence under a governance agreement.
They both knew that.
They had been planning around it.
Then Whitmore Tower Holdings failed.
The headlines called me bankrupt.
Daniel saw the failure as proof I no longer deserved voting control.
Marcus saw it as something to endure until succession.
Neither understood the failed tower represented less than eight percent of my personal net worth and sat inside a separate LLC structure.
I had personal guarantees on a limited portion.
Painful.
Not ruinous.
I did not correct the press aggressively.
Why?
Pride, oddly enough.
I did not want to publish my balance sheet merely to prove I remained rich.
Daniel hated that.
“You’re letting the market think you’re insolvent.”
“I am not the company.”
“You are our founder.”
“Then maybe the founder can survive a bad investment.”
“You don’t understand reputation anymore.”
That word.
May you like



Anymore.
Everything I had built slowly became evidence I was too old to manage it.







